Why Did Mortgage Rates Go Up? Sometimes the Answer Isn't in the Headlines
Why Did Mortgage Rates Go Up? Sometimes the Answer Isn't in the Headlines
Oil prices fell yesterday. The economic news was pretty quiet.
And mortgage rates went up anyway.
If you're buying a home—or even just watching mortgage rates waiting for the "right time"—that can feel like it makes absolutely no sense.
But honestly, yesterday was a pretty good example of something I wish more homebuyers understood:
Not every mortgage rate move has a clean headline attached to it.
And trying to predict every move can drive you nuts.
What happened to mortgage rates yesterday?
Mortgage rates moved higher again Tuesday.
Mortgage News Daily's top-tier 30-year fixed mortgage rate index increased from 7.50% to 7.58%, its highest level since November 1, 2023.
Normally, we'd start looking for the obvious culprit.
Oil?
Nope. Oil prices actually had a pretty significant drop.
Big economic report?
Not really.
The August JOLTS report showed about 7.1 million job openings, little changed from the previous month. Mortgage News Daily said Tuesday's economic data wasn't the driver behind the increase in rates.
So...
Why did mortgage rates go up?
Here's where mortgage rates get a little weird.
Sometimes the answer has less to do with a major economic headline and more to do with what's happening inside the bond market itself.
Today is the last trading day of the quarter. Around quarter-end, large investors like pension funds, banks, and asset managers can rebalance their portfolios. That's a lot of buying and selling happening in a pretty short window.
Mortgage News Daily pointed to quarter-end trading and existing bearish momentum as likely contributors to this week's bond-market weakness.
Translation?
Sometimes mortgage rates move because the market is doing market things.
There isn't always a giant flashing headline that explains it.
And no, that doesn't mean rates automatically improve tomorrow, October 1.
Nobody knows that.
Including me.
That's kind of the point.
Do mortgage rates follow the 10-year Treasury?
Yes—but this is where people get confused.
You'll hear me talk about the 10-year Treasury yield a lot because it's one of the best benchmarks for understanding the general direction of mortgage rates.
But your mortgage rate is not simply the 10-year Treasury yield plus some fixed number.
Mortgage rates are more directly tied to mortgage-backed securities, or MBS. Those are securities backed by pools of mortgages that trade in the bond market.
Treasuries and mortgage-backed securities usually move in the same general direction, which is why the 10-year gets so much attention.
But they don't move perfectly together.
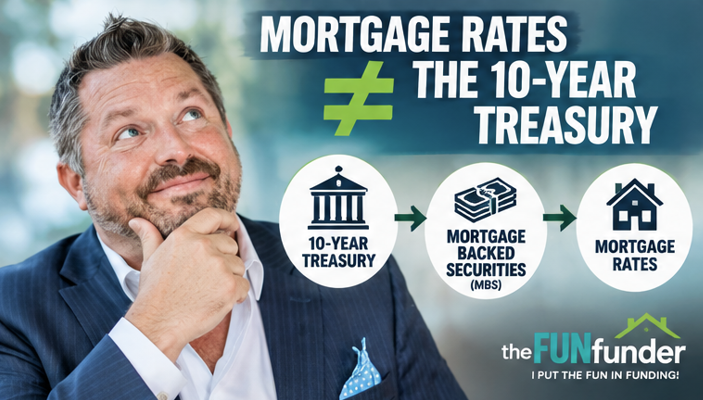
On Tuesday, the 10-year Treasury reached its highest levels since 2007, while mortgage rates were at their highest levels since late 2023. Mortgage News Daily specifically noted that mortgage-backed securities have been outperforming Treasuries compared with 2023.
That's an important distinction.
Because seeing:
"10-YEAR TREASURY HITS 2007 LEVELS!"
doesn't mean you should immediately assume your mortgage rate just did the same thing.
What actually causes mortgage rates to change?
There isn't one magic number.
Mortgage rates can react to things like:
Inflation
Federal Reserve expectations
Economic growth
Treasury yields
Mortgage-backed securities
Bond-market supply and demand
Geopolitical events
Investor positioning and trading
And sometimes several of those things are pulling in different directions at the exact same time.
That's why answering "Why did mortgage rates go up today?" isn't always as simple as pointing to one economic report.
Yesterday was a perfect example.
Are home prices falling because mortgage rates are higher?
Not nationally, at least according to the latest FHFA data.
The FHFA House Price Index showed U.S. home prices increased 0.3% in July and were 2.6% higher than July 2025.
That's not runaway appreciation.
But it's also not the big nationwide price collapse some buyers have been waiting for.
And that's where waiting gets tricky.
To get the "perfect" buying environment, you might be waiting for:
Lower mortgage rates and lower home prices and more inventory and less competition.
Could that happen?
Sure.
Do I know when?
Nope.
Neither does the guy yelling about rates on TikTok.
Stop trying to beat the mortgage market
I understand why buyers do it.
"Maybe rates will drop next month."
Maybe.
"Maybe I'll wait until after the Fed meeting."
Okay.
"Maybe the 10-year comes back down."
It might.
But yesterday is exactly why I don't love building a homebuying plan around predictions.
Oil dropped.
The economic data wasn't particularly dramatic.
Rates still went up.
You can't control the bond market. But you can control whether you're ready when an opportunity makes sense.
That's a much better place to spend your energy.
What homebuyers can actually control
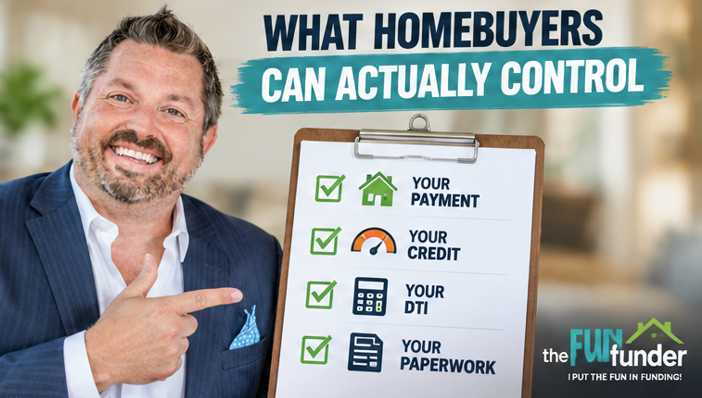
Instead of trying to predict tomorrow's mortgage rate, focus on these four things.
1. Your comfortable monthly payment
Not the absolute maximum a lender says you can qualify for.
I want to know the payment where you can still live your life, go out to dinner, take a vacation, and sleep at night.
2. Your credit
Know where you stand. Pay everything on time.
And please don't open a new credit card because Target offered you 15% off while you're trying to buy a house.
3. Your debt-to-income ratio
Your debt-to-income ratio (DTI) compares your monthly debt payments with your gross monthly income.
Higher mortgage rates can increase the projected house payment, which can push your DTI higher.
That's why managing the debts you can control matters even more when rates rise.
4. Your mortgage paperwork
Pay stubs. W-2s. Bank statements. Down-payment funds.
Get organized before you find the house.
Boring?
Absolutely.
Helpful when you suddenly find THE house on Saturday afternoon?
Very.
So, should you wait for mortgage rates to come down?
That's not really a mortgage-rate question.
It's a home-readiness question.
If buying today would stretch your budget beyond what you're comfortable with, we build a plan.
If you're six months away because you need to improve your credit or save more money, we build a plan.
If you're ready now and the right house shows up, we figure out what the numbers actually look like.
That's what I mean when I say:
Preparation beats prediction.
You don't need to correctly predict the bond market.
You need to know your numbers.
Find out where you stand
If you're thinking about buying a home and you're not sure whether you're actually mortgage-ready, start with my Homeownership Readiness Score™.
It takes a couple of minutes. No credit pull. No awkward sales call. No cost.
You'll get a clearer picture of where you stand today—and what you may want to work on before you start seriously shopping.
👉 Take the Homeownership Readiness Score™:
https://thefunfunder.com/readiness-score-page
We don't guess. We make a plan.
Josh Catigano | the FUN funder | CMG Home Loans | NMLS #1817426 | Equal Housing Opportunity
"I put the FUN in funding!"
Market information referenced from Mortgage News Daily, MBS Highway, the U.S. Bureau of Labor Statistics, and the Federal Housing Finance Agency based on reports available September 29–30, 2026. Mortgage rate indexes and market commentary are for educational purposes and are not an offer or quote of credit from CMG Home Loans. Treasury yields are not consumer mortgage rates. Mortgage rates vary based on borrower qualifications, loan program, property, market conditions, and other factors. This information is for educational purposes only and is not a commitment to lend. All loans are subject to approval.