The 10-Year Treasury Just Crossed 5%. Here's What It Means for Mortgage Rates (and What It Doesn't).
You're going to see “5%” in a lot of headlines today.
Let's take the scary out of it.
What happened this morning
Per MBS Highway (9/23/2026), the 10-year Treasury yield opened around 4.97% and climbed to about 5.07% by late morning.
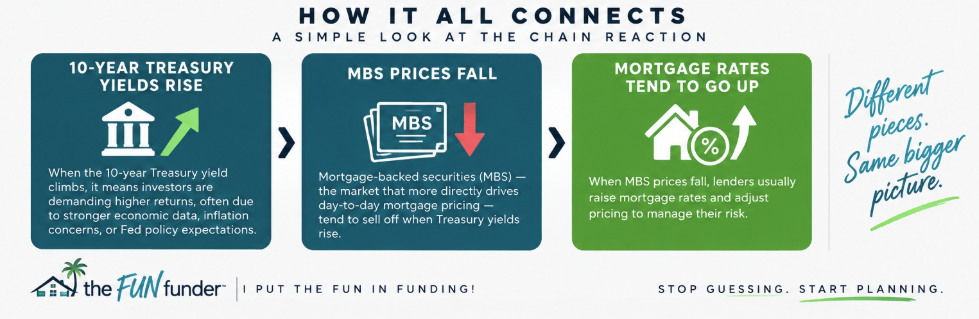
Mortgage-backed securities — the market that more directly drives day-to-day mortgage pricing — sold off hard at the same time.
MBS Highway sent out a lock alert before lunch.
Their morning update pointed to a couple of major factors, including:
Stronger manufacturing data. When the economy looks hotter, bond investors can become more concerned about inflation and demand higher yields.
Movement in oil prices and bond yields, adding more volatility to an already jumpy market.
Those were some of the forces moving markets this morning. No secret mortgage-rate switch — just markets reacting quickly to new information.
Why a government bond matters to your mortgage
Quick plain-English version.
The 10-year Treasury is one of the major benchmarks for long-term borrowing in the U.S., and mortgage rates tend to move in the same general direction.
Not perfectly. There's a spread between Treasury yields and mortgage rates that changes over time, and mortgage-backed securities have a more direct impact on day-to-day mortgage pricing.
But when the 10-year climbs quickly and mortgage-backed securities sell off, mortgage pricing will usually get worse.
So when you hear “the 10-year crossed 5%,” the useful translation for a homebuyer is:
Today was a rough day for mortgage rates.
That's true. I'm not going to sugarcoat it.
The part the headlines skip
The same MBS Highway morning update also noted that home values remain stable despite the challenges.
Read that again next to the rate news.
Rates had a bad morning. Home values didn't suddenly fall with them.
That matters because a lot of buyers carry around a quiet assumption:
“If rates go up, prices will drop, so I'll wait.”
Maybe.
Maybe not.
I'm not telling you that to rush anybody into buying a house. I'm telling you because waiting for the market to hand you a perfect moment isn't a strategy. It's a hope.
5% is a headline, not a plan
Round numbers get attention.
5% sounds dramatic in a way 4.97% doesn't, even though the difference is tiny.
I'm also not going to tell you where the 10-year Treasury goes next. Nobody knows. Markets can move quickly in either direction.
Here's what you can know today, regardless of what bonds do tomorrow:
1. Your comfort payment
Not just what a lender says you qualify for.
What would you actually be comfortable paying every month without feeling house-poor?
That's the number that matters.
2. Your credit, right now
What's on the report?
What's helping?
What's hurting?
And is there anything that could realistically be improved before you buy?
3. Your paperwork
Pay stubs. W-2s. Bank statements. Employment history.
Know what you're going to need and have it ready.
Buyers who know those three things don't have to panic on days like today.
They adjust.
A rough rate day might shift the price range a little. It might change the conversation about points, seller credits, loan programs, or when to lock.
It doesn't have to blow up the plan — because there is a plan.
Whether you're buying in Charleston, elsewhere in South Carolina, or one of the other markets I serve, the same principle applies:
You don't need to predict the bond market. You need to know your numbers.
If you're already under contract
Don't doom-scroll.
Call or text your loan officer and have a calm conversation about your options and lock timing.
That's what days like this are for — a planning call, not a panic call.
If you're not there yet
Start with where you stand.
My Homeownership Readiness Score™ takes about 60 seconds.
No credit pull. No cost. No guessing.
You'll get a clearer picture of where you stand today and what your next move should be.
Get your Homeownership Readiness Score™ →
https://thefunfunder.com/readiness-score-page
Don't time the market. Prepare for it.
Josh Catigano
the FUN funder
CMG Home Loans | NMLS #1817426
Equal Housing Opportunity
“I put the FUN in funding!”
Market information referenced from the MBS Highway Daily Morning Update and Alert to Lock dated September 23, 2026. Treasury yields and mortgage-backed securities prices are not consumer credit terms and are not mortgage rates. This article is for general educational purposes and is not an offer of credit. Interest rates and loan terms vary based on borrower qualifications, loan program, property, and market conditions. This is not a commitment to lend.