Debt-to-Income Ratio: The Half of the Math You Control When Rates Rise
Debt-to-Income Ratio: The Half of the Math You Control When Rates Rise
Home Readiness Tip
Rates went up again.
So what can you actually do about it?
More than you might think. Just not on the side everyone's watching.
What happened this week
Yesterday, average mortgage rates matched their highest level since May 2024, according to Mortgage News Daily. A stronger-than-expected business activity report helped push the 10-year Treasury above 5.1%.
This morning, yields moved even higher. The 10-year Treasury reached roughly 5.17%, while mortgage-backed securities sold off again.
Quick translation:
Mortgage rates tend to move in the same general direction as the 10-year Treasury. When Treasury yields rise and mortgage-backed securities lose value, mortgage pricing generally gets worse.
You don't control that.
Neither do I. Neither does your real estate agent.
So instead of staring at the part of the equation we can't control, let's talk about the part we can.
What is a debt-to-income ratio?
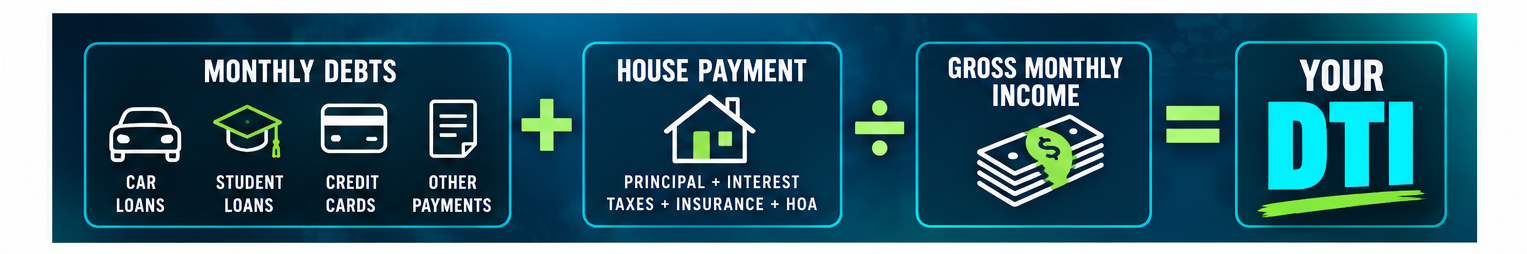
Your debt-to-income ratio, or DTI, is one of the most important numbers in your mortgage file.
Here's the plain-English version:
Add up your monthly debt payments — things like car loans, student loans, credit card minimum payments and personal loans.
Add your proposed new house payment — principal, interest, property taxes, homeowners insurance and, when applicable, HOA dues.
Divide that total by your gross monthly income. Gross means your income before taxes and other deductions.
That's your debt-to-income ratio.
Lenders use DTI as one part of determining how much monthly housing expense and debt you may be able to carry.
Different loan programs and borrower scenarios can have different requirements, so there isn't one universal DTI number that works for everybody.
Why rising rates squeeze your DTI
Here's where today's mortgage market enters the equation.
A higher mortgage rate means a higher monthly payment on the same loan amount.
Higher house payment + same income = higher DTI.
That's one reason buyers can suddenly feel “priced down” when rates move higher.
The house didn't change.
The math did.
But here's the important part:
Your existing monthly debts are the part of that equation you often have the most ability to influence.
You can't personally move the 10-year Treasury.
You can understand and manage what's happening on your side of the equation.
Three DTI moves you can make this week
1. Know every monthly payment
Not just the balance.
The monthly payment.
Check your credit report and your actual monthly obligations instead of relying on memory.
People forget about the store card they opened months ago, an old payment plan, a small personal loan or financing they barely think about anymore.
Your loan officer can tell you which obligations need to be included for your specific loan program.
The important thing is knowing what's there before you're trying to qualify for a house.
2. Don't casually add a new payment
This one is huge.
A new car payment before closing can change your qualifying numbers very quickly.
The same goes for opening a new credit card, financing furniture or putting appliances on a store account.
That doesn't mean you can never buy anything again.
It means timing matters when you're preparing for a mortgage.
If you're planning to buy a home, talk to your loan officer before taking on new debt.
The couch will still be there after closing. I promise.
3. Don't pay things off blindly
This surprises people.
Paying off debt sounds like an automatic win.
Sometimes it is.
Sometimes it isn't.
For example, eliminating a relatively small balance that carries a large monthly payment may have a meaningful impact on your DTI.
Throwing a large amount of cash at a debt with a relatively small required monthly payment might not change the qualifying math nearly as much.
And there's another side to the decision.
Every dollar you use to eliminate debt is a dollar you no longer have available for your down payment, closing costs or reserves.
That's why I don't like borrowers randomly moving money around just because something sounds like the right move.
Run the numbers first.
The best move depends on your entire mortgage file.
Buyers are still buying
There's another important piece of context from this week's market.
Despite higher rates, new-home sales have continued to show resilience.
People are still buying homes.
The buyers who make it to the closing table usually aren't the people who perfectly predicted where mortgage rates were going.
They're the people who understood their payment, income, debts and potential roadblocks before they wrote the offer.
You can't control the 10-year Treasury.
You can control your side of the ratio.
Preparation beats prediction.
Find out where you stand
Not sure what your DTI looks like—or what else might be standing between you and buying a home?
Start with my Homeownership Readiness Score™.
It takes about 60 seconds.
No credit pull. No cost. No guessing.
You'll get a clearer picture of where you stand today and what your next move should be.
Get your Homeownership Readiness Score™ →
https://thefunfunder.com/readiness-score-page
Josh Catigano
the FUN funder
CMG Home Loans | NMLS #1817426
Equal Housing Opportunity
“I put the FUN in funding!”
Market data referenced from Mortgage News Daily, September 23, 2026, and MBS Highway market updates dated September 24, 2026. Treasury yields and mortgage-backed securities prices are not consumer credit terms or mortgage rates. Debt-to-income information in this article is general education and is not a promise of any loan result. Treatment of individual debts, qualifying income, DTI requirements and underwriting guidelines vary by loan program and borrower circumstances. All loans are subject to underwriting approval. Interest rates and loan terms vary based on borrower qualifications, loan program, property and market conditions. This is not a commitment to lend.