Keep Your Mortgage File Fresh: Be Ready When Rates or the Right House Move
Keep Your Mortgage File Fresh: A Good Rate Day Doesn't Help If You Aren't Ready
Yesterday, mortgage rates finally gave buyers a little bit of a break.
And I don't mean one of those microscopic moves where technically rates improved, but nobody outside the mortgage world would ever notice. Mortgage News Daily called the move “a rarity these days.”
Great. I’ll take it.
But here's the question I think buyers should actually be asking:
If yesterday had been the day you found the house you wanted, would you have been ready to take advantage of it?
Because I've seen this happen plenty of times. Someone got pre-approved a month or two ago. They started looking. Life happened. The house search slowed down.
Then suddenly — there it is.
The house.
And now we're digging around for updated bank statements, new pay stubs and figuring out whether anything has changed since we last looked at the file.
That's why I tell buyers: keep your mortgage file fresh.
What happened yesterday?
The short version: mortgage rates moved meaningfully lower.
The 10-year Treasury got as high as roughly 5.34% during the day before finishing closer to 5.24%. Mortgage bonds also improved, which generally helps mortgage rates.
And here's the interesting part: there wasn't one giant piece of news that caused it.
Mortgage News Daily basically said the same thing. There wasn't one obvious reason for the move, and the next big jobs report could easily change the tone again.
Could rates keep improving?
Sure.
Could they turn around and go the other direction?
Absolutely.
I don't know. Neither does anybody else.
And that's exactly the point.
You don't have to predict the market. You need to be prepared for it.
Your mortgage file has a shelf life
I explain it to buyers like this:
Your mortgage file is a little like the milk in your refrigerator.
It's perfectly good when it's fresh. But you can't leave it sitting there forever and expect everything to still be good to go.
When I pre-approve someone, I'm looking at a snapshot of their financial picture at that moment:
Your income.
Your assets.
Your debts.
Your credit.
Your employment.
But life doesn't stop because you got pre-approved.
Pay periods change. Bank statements change. Credit balances change. Jobs change. And eventually some of the documentation we used gets old.
That doesn't mean something is wrong with your loan.
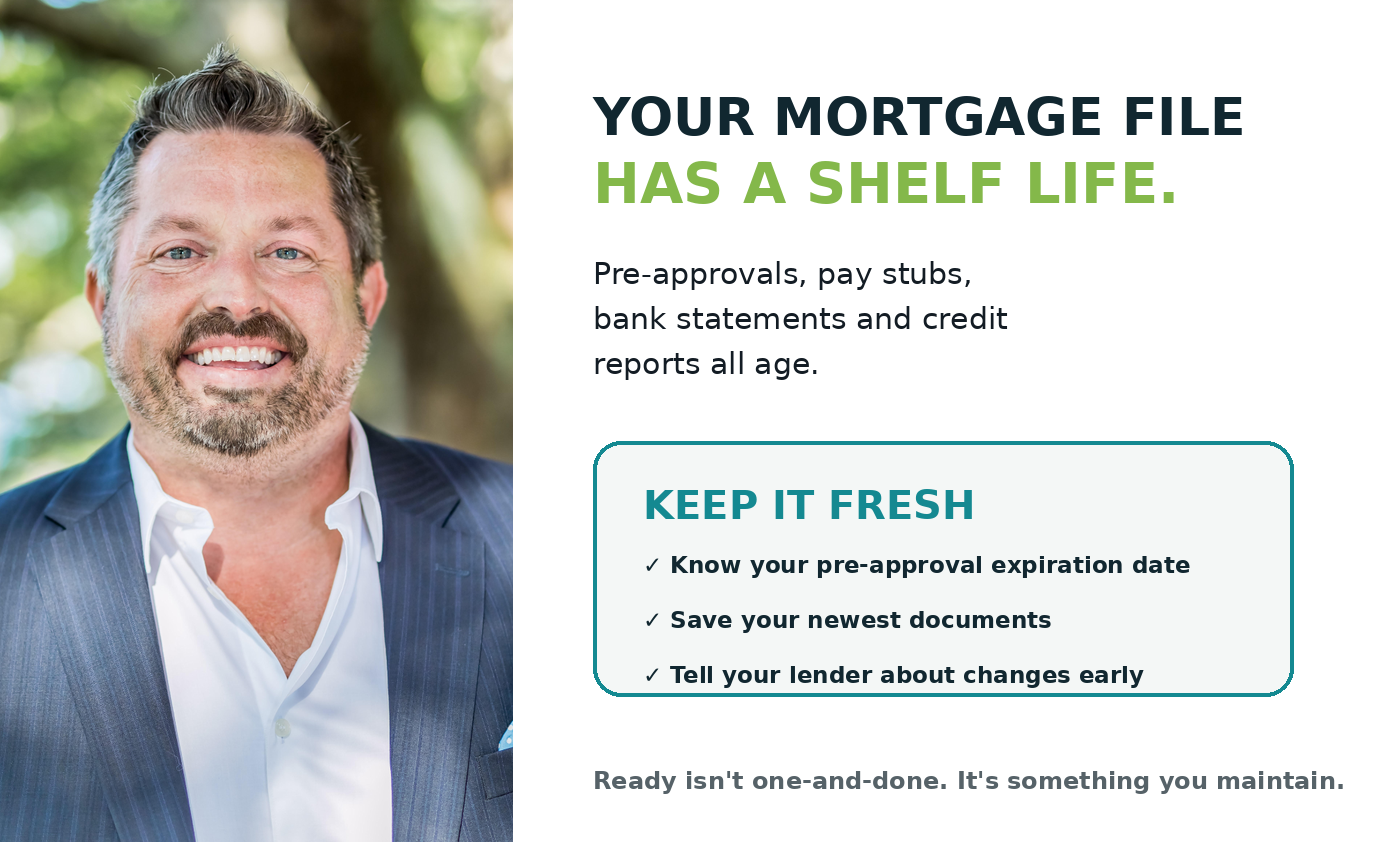
It just means we need to keep the file fresh.
5 easy ways to keep your mortgage file fresh
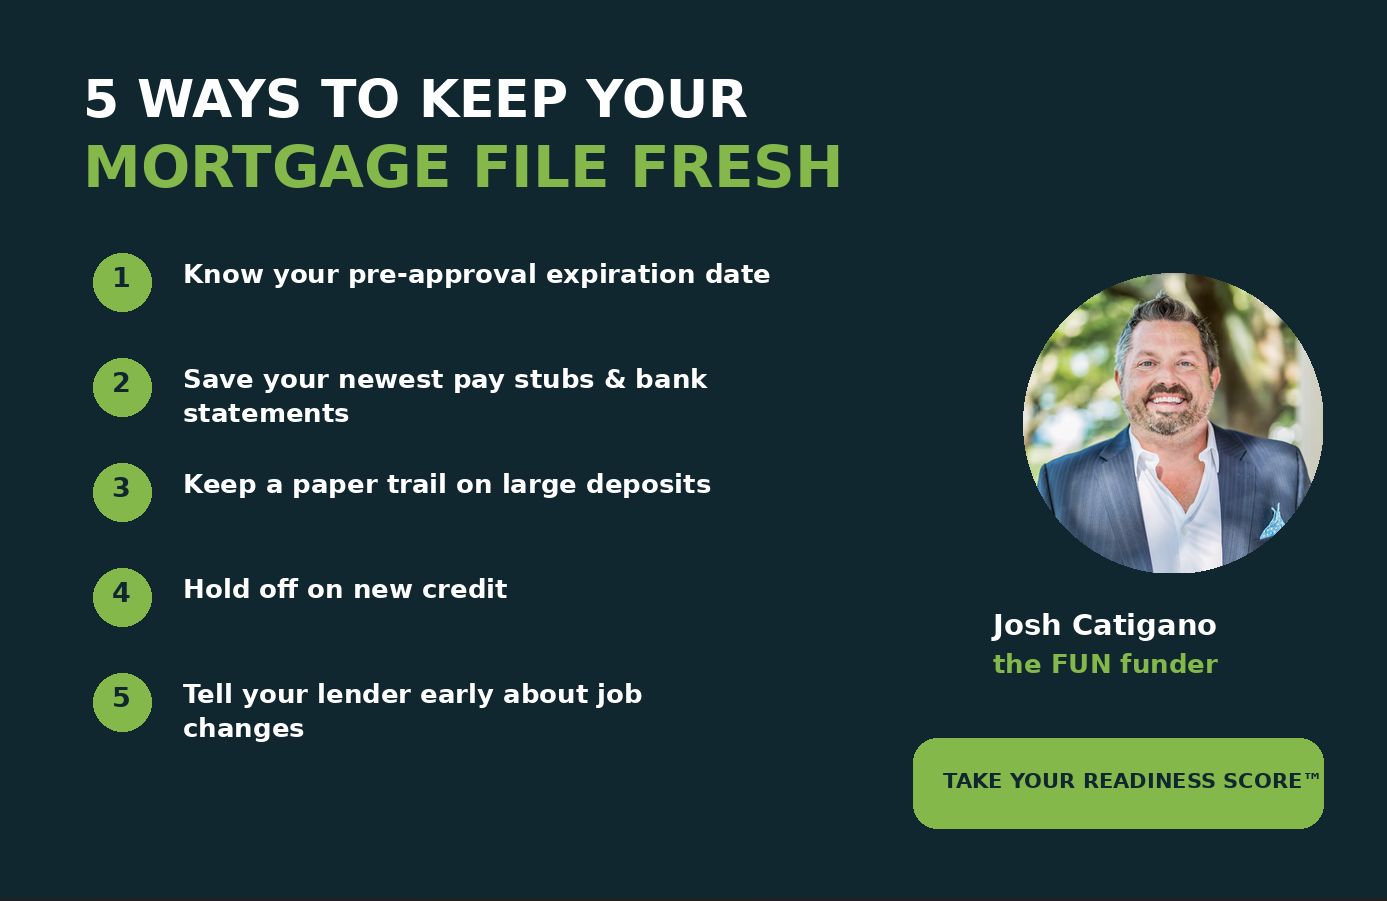
1. Know when your pre-approval needs to be updated
Don't wait until you find the perfect house to ask.
If you've been looking for a while, just check in with your lender.
A quick refresh ahead of time is easy.
Trying to refresh everything while your Realtor is asking, “So...are we writing this offer?” is considerably less fun.
2. Keep your newest pay stubs and bank statements
This one is ridiculously easy.
Make a folder on your computer or phone. Call it HOUSE STUFF, MORTGAGE, JOSH WON'T STOP ASKING ME FOR DOCUMENTS — I don't care. 😂
Every month, throw your newest pay stubs and bank statements in there.
Five minutes.
Future-you will be very happy you did it.
3. If money suddenly shows up in your account, keep the paper trail
Bonus from work?
Sold a car?
Gift money from Mom and Dad?
Moved money between accounts?
Keep the documentation.
One of the most common questions in mortgage underwriting is basically:
“Where did this money come from?”
It's much easier to answer that question when it happened three days ago instead of trying to reconstruct it three months later.
4. Please don't finance a truck while you're house shopping
Or a boat.
Or a couch.
Or open three credit cards because somebody offered you 15% off today's purchase.
I've seen versions of all of these.
New debt can change your debt-to-income ratio and potentially change how much house you qualify for.
Before you finance something significant while you're buying a home, call me first.
I'd much rather have a two-minute conversation before you buy it than a considerably less fun conversation afterward.
5. Tell me about job changes BEFORE they become surprises
Got a raise? Awesome.
New job? Congratulations.
Going from salary to commission? We should talk.
Changing from W-2 to self-employed?
Definitely call me. 😂
None of those things automatically mean you can't buy a house. But different types of income can have different documentation and history requirements.
The earlier I know, the more options we have.
Why does keeping your mortgage file fresh matter?
Because good market days don't make appointments.
Yesterday was a perfect example.
Rates improved.
Nobody sent homebuyers an invitation a week ago saying:
“Please have your financial documents ready Thursday. Mortgage rates may cooperate.”
It just happened.
And houses work the same way.
You can look for six weeks and find absolutely nothing you love.
Then Tuesday morning your Realtor texts:
“Josh...this might be the one.”
That's when preparation matters.
If your mortgage file is fresh, we're updating a few things and getting to work.
If your file hasn't been touched in three months, now we're rebuilding things while the clock is ticking.
And here's the part I really want buyers to understand:
Staying ready does NOT mean you have to buy.
It means that when the right house, the right payment and the right opportunity come together, you get to decide.
You're not sitting on the sidelines because your paperwork wasn't ready.
Stop trying to perfectly time mortgage rates
I understand why buyers do it.
"Maybe rates drop next month."
They might.
"Maybe they'll be lower next spring."
Maybe.
But you're trying to predict something influenced by inflation, employment, the Federal Reserve, Treasury markets, mortgage-backed securities, geopolitics and about 900 other things before breakfast.
That's a tough way to buy a house.
I'd rather focus on the things we can control.
Your comfortable monthly payment.
Your credit.
Your cash.
Your documents.
Your timeline.
Your plan.
Preparation beats prediction.
Every time.
Not sure how ready you actually are?
That's exactly why I built the Home Readiness Score™.
It gives you a quick look at where you stand right now and what your next step should be — whether you're ready to start looking or you're still a few months away.
No pressure. No commitment. Just some clarity.
Take your Home Readiness Score™ here:
Because the goal isn't to guess which day rates will be perfect.
The goal is to be ready when your day shows up.
Josh Catigano | the FUN funder
CMG Home Loans | NMLS #1817426
Equal Housing Opportunity
I put the FUN in funding!
Market information referenced from Mortgage News Daily and MBS Highway, 10/1/2026, and is for educational purposes only. Rates vary based on borrower qualifications, loan program and market conditions. Pre-approval is subject to lender review and verification. This is not a commitment to lend.