How AI Is Changing the Mortgage Industry | the FUN funder
AI Is Changing the Mortgage Industry. But Are We Using It to Fix the Right Problems?
The future of mortgage lending isn't less human. It's less paperwork, less waiting, fewer surprises, and a whole lot more clarity.
I've spent more than 20 years in real estate, and I've watched our industry go through some pretty significant changes.
We went from fax machines and stacks of paper to electronic signatures, online applications, automated underwriting, and digital document collection.
Every advancement promised to make the mortgage process faster, easier, and more efficient.
And yet, here we are.
Borrowers still get asked for documents they've already provided. Realtors still chase down updates. Loan officers still spend hours entering information into systems that don't always communicate with each other.
Now artificial intelligence is entering the picture in a big way.
And I believe we have an opportunity to do something much bigger than simply speed up the same old process.
We have an opportunity to rethink the process entirely.
AI Is Already Changing Mortgage Lending
This isn't some futuristic concept anymore.
Artificial intelligence, machine learning, and automated data verification are already influencing how mortgage lenders evaluate information, manage risk, identify errors, and process loans.
For example, Freddie Mac has expanded automated capabilities that help lenders assess income, employment, and assets using verified financial data.
That's a meaningful advancement.
Instead of making a borrower repeatedly track down paperwork, technology can help verify information directly through approved channels.
Fannie Mae has also established a governance framework for how its seller/servicers use AI and machine learning in mortgage origination and servicing.
In other words, this isn't just about experimenting with ChatGPT anymore. AI is becoming part of the infrastructure of mortgage lending.
But here's the question I think our industry needs to ask:
Are we using AI to create a better experience, or just to make the existing process more profitable?
Ideally, the answer should be both.
The Real Problem Isn't a Lack of Technology. It's a Lack of Integration.
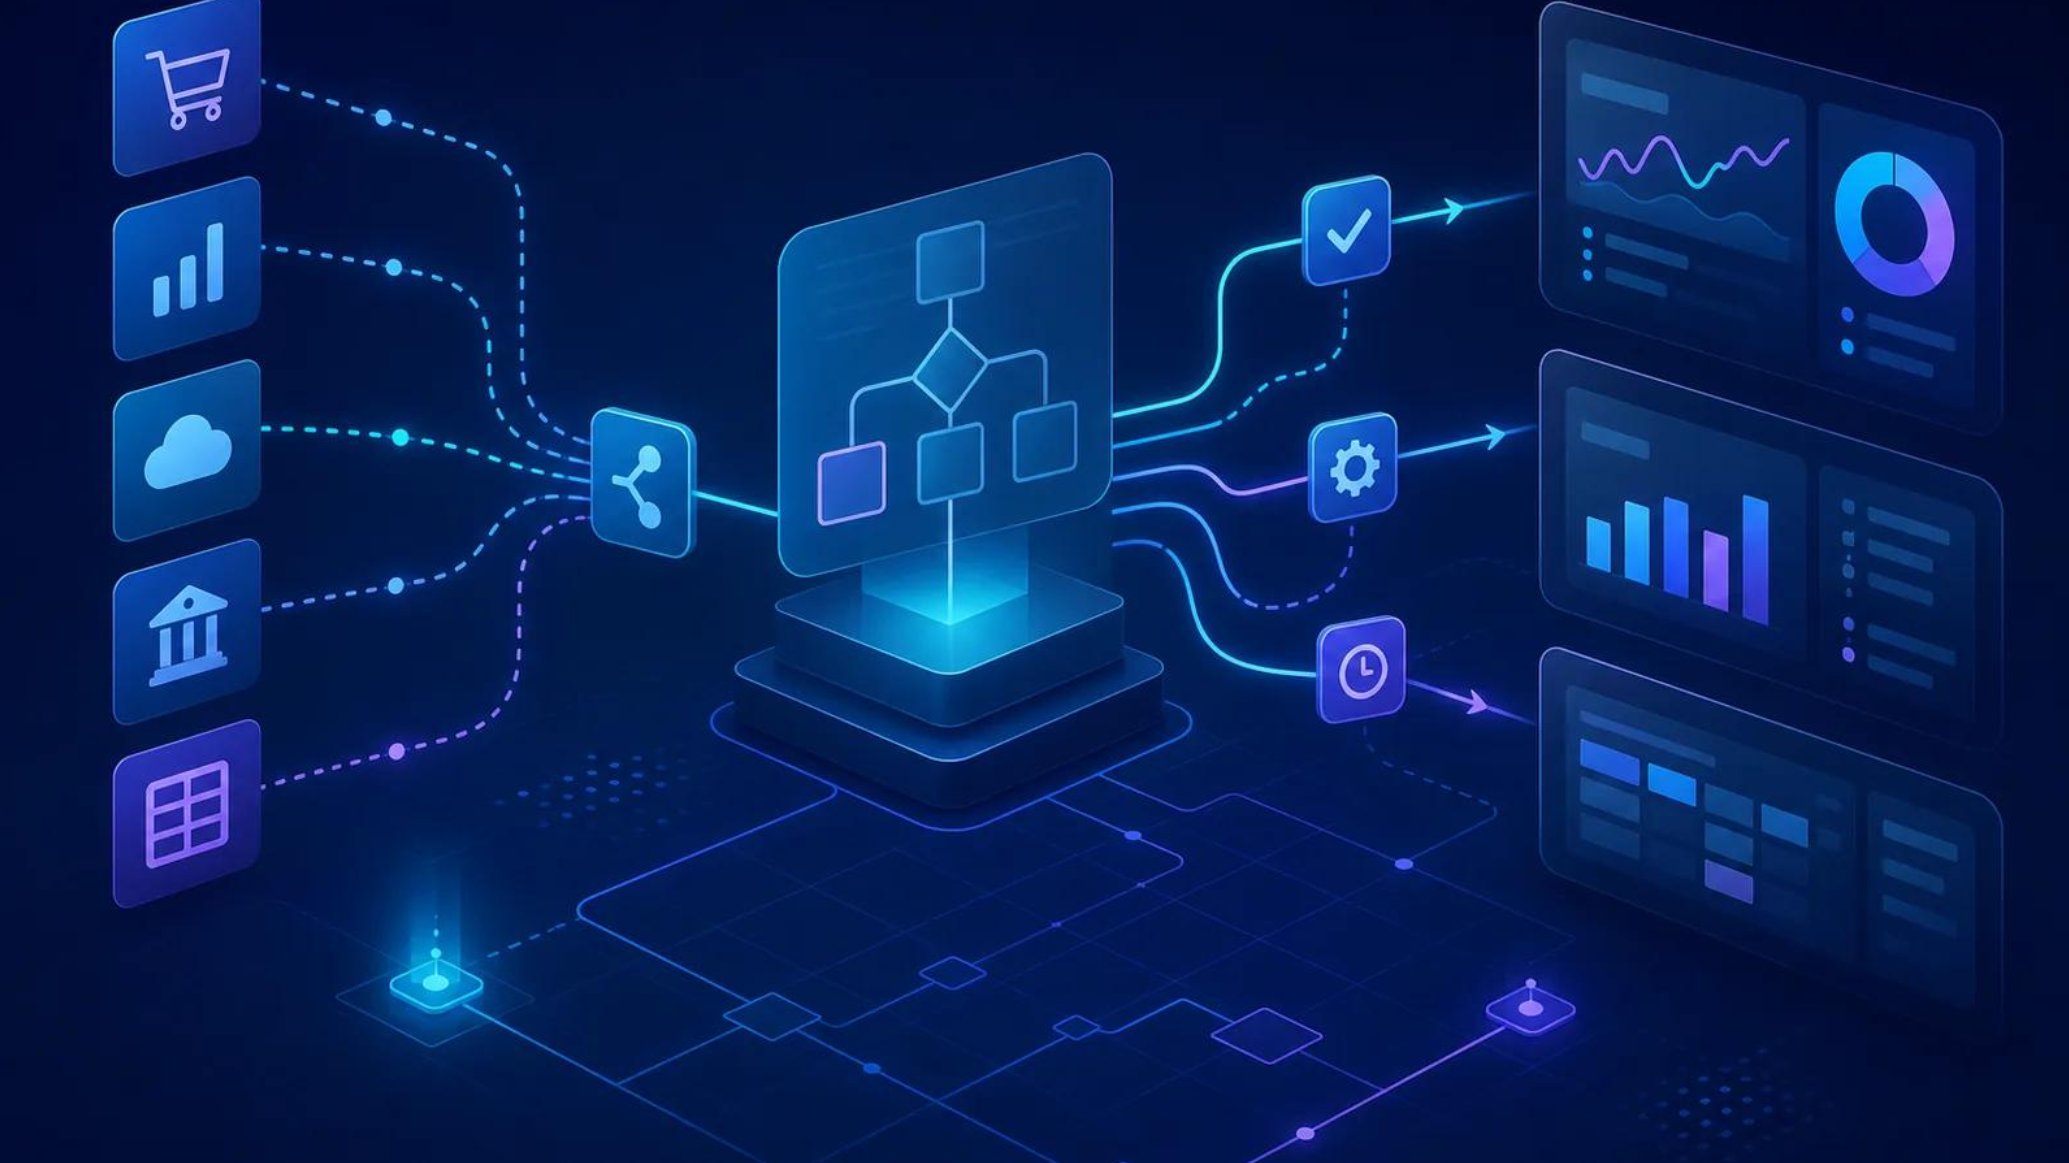
Think about how many different systems are involved in getting someone from their first homebuying question to the closing table.
There's the CRM, loan origination system, document portal, credit reporting system, automated underwriting engine, pricing engine, title company, insurance provider, appraisal process, and a collection of communication tools.
Many of these systems are impressive individually.
But when they don't communicate effectively, people become the connection between them.
And that's where things break down.
Information gets entered twice. Updates get missed. Emails pile up. Important details get buried.
The result?
Loan officers spend less time advising clients. Realtors spend more time chasing information. Borrowers are left wondering what's happening with their loan.
That's the problem I want AI to solve.
Not simply writing a better email, but helping ensure the email doesn't need to be written in the first place.
Imagine What the Mortgage Experience Could Look Like
Picture a buyer beginning their homeownership journey.
Instead of filling out a generic application and hoping for the best, they start with a guided conversation about their goals, income, budget, timeline, and concerns.
AI helps organize that information, identify what might be missing, and prepare the loan officer for a more productive conversation.
The loan officer then reviews the information, verifies what's appropriate, and helps the buyer understand their options.
No guesswork. No unnecessary back-and-forth.
Now imagine that buyer finds a home.
Their financing information is already organized. Relevant documents have been securely collected. Potential issues have been flagged early.
As the loan moves forward, approved systems coordinate updates and identify outstanding items.
The buyer knows what comes next.
The Realtor has timely, accurate information about the transaction.
And the loan officer can spend more time solving problems instead of hunting for them.
That's the mortgage experience I'd like to see.
And importantly, that's a vision for the future—not a claim that every lender can deliver it today.
READY TO STOP GUESSING AND START PLANNING?
Technology can make the mortgage process easier, but understanding your own homebuying readiness is still the best place to start.
Get Your Homeownership Readiness Score™
The Loan Officer of the Future Should Be More Valuable, Not Less
There's a lot of discussion about whether AI will eventually replace mortgage loan officers.
I think that question misses something important.
A mortgage isn't just a math problem.
It's a financial decision involving someone's income, savings, family, lifestyle, and long-term goals.
Two borrowers with identical financial profiles might need completely different strategies.
One might want to maximize purchasing power. Another might prioritize keeping monthly expenses low. Someone else might be navigating self-employment income, a complicated credit history, or the sale of an existing home.
AI can help organize information, compare scenarios, and identify possibilities.
But the professional's job is to understand what those possibilities mean for the person sitting across the table.
Technology should make good loan officers better—not turn borrowers into numbers on a screen.
The loan officers who thrive will be the ones who combine strong mortgage knowledge, sound judgment, personal relationships, and the ability to use technology effectively.
What About Realtors?
I believe Realtors stand to benefit tremendously from thoughtful AI integration.
Imagine having accurate transaction updates without making three phone calls.
Imagine receiving early warnings about documentation issues that could affect closing.
Imagine being able to spend more time helping clients find the right home and negotiate effectively instead of tracking down routine status information.
AI could also help agents organize their databases, prioritize follow-ups, prepare listing materials, research neighborhoods, and maintain meaningful relationships with past clients.
But just like mortgage lending, the opportunity isn't to automate the relationship.
It's to eliminate the repetitive work that gets in the way of building one.
We Also Need to Talk About the Risks
I'm excited about AI, but I don't believe we should blindly hand over the keys.
Mortgage lending involves highly sensitive financial information and decisions that can have enormous consequences for consumers.
Accuracy, privacy, security, fairness, and accountability must come first.
AI systems can make mistakes. They can produce convincing but incorrect information. Poorly designed models can create unfair outcomes.
And when technology contributes to a lending decision, lenders still have legal and regulatory responsibilities.
That means the future needs more than powerful software.
It needs appropriate human oversight, approved data handling, transparent processes, and professionals who understand the limitations of the tools they're using.
Faster isn't better if it comes at the expense of trust.
Here's What I Think the Industry Should Be Working Toward
I see five priorities for the next generation of mortgage technology:
1. Systems that actually communicate. Information should move securely between authorized platforms without constant manual reentry.
2. Proactive problem-solving. Technology should help identify missing documentation, inconsistencies, and potential delays before they become emergencies.
3. A more transparent borrower experience. Homebuyers should understand where they are, what's next, and who is responsible for each step.
4. More personalized financial guidance. Loan officers should have better tools to explain options in ways that reflect each borrower's actual goals and comfort level.
5. More time for human relationships. Automation should give mortgage professionals and Realtors more capacity to advise, educate, and serve—not just handle a higher volume of transactions.
The Future Isn't AI vs. Humans. It's AI Working With Humans.
I don't think the mortgage industry needs another dozen disconnected apps promising to revolutionize everything.
We need technology that works together.
We need processes designed around the people using them.
And we need to stop measuring innovation solely by how many tasks we can automate.
The real measure should be whether we're making homeownership easier to understand, less stressful, more transparent, and more accessible.
That's the future I'm excited about.
Because after more than two decades in real estate, one thing hasn't changed:
People don't just need a mortgage. They need someone they trust to help them make a smart decision.
If AI helps us deliver that experience better, I'm all for it.
And if it means fewer unnecessary emails, fewer last-minute surprises, and a little more FUN in funding?
Even better.
The Future of Lending Is Personal
AI is changing how we work, but great mortgage advice will always start with understanding you.
Whether you're buying your first home, planning your next move, or simply exploring your options, I'm here to help you put together a plan.
Discover Your Homeownership Readiness Score™
Stop Guessing. Start Planning.
About the author
Josh Catigano is a mortgage loan originator with CMG Home Loans and the voice behind the FUN funder. With more than 20 years of experience in real estate, he focuses on helping buyers understand their financing options, make informed decisions, and approach homeownership with confidence.
Stop Guessing. Start Planning.
Discover Your Homeownership Readiness Score™
Josh Catigano | NMLS #1817426
CMG Home Loans | NMLS #1820
This article reflects the author's perspective on technology and mortgage lending. AI-assisted tools do not replace professional review, underwriting requirements, or applicable consumer protections.